


 No single product gives you the highest income along with certainty, full access to capital and a guaranteed inheritance. (Photo: iStock)
Question:
I am 65 and have a retirement fund worth R5-million. I want an income, but I also want to leave something to my son when I die. What should I do?
Answer:
Balancing the income you need today with the desire to leave capital to your family later is a challenge that affects many.
There are several options, but no single product gives you the highest income along with certainty, full access to capital and a guaranteed inheritance. Here are a number of options you can consider so that you and your planner can make a better decision.
1. Living annuity
With a living annuity, your R5-million remains invested and you choose an income of between 2.5% and 17.5% of the value each year. The recommended drawdown rate for a 65-year-old is 5%.
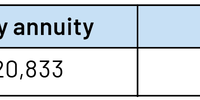
If you are able to live on R19,000 a month and your funds are correctly invested, there should be a decent inheritance for your son, as whatever remains in the living annuity when you die can be passed on to him. The trade-off is that neither your income nor the capital is guaranteed.
2. Guaranteed life annuity
With a guaranteed life annuity, you give an insurer a lump sum in exchange for a pension guaranteed for as long as you live. This removes investment and longevity risk.
You can choose a level income or one that increases each year. You can also select a guarantee period – for example five, 10 or 20 years. If you die during that period, the income continues to your nominated beneficiary until the guarantee period ends.
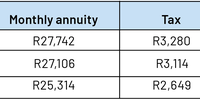
The longer the guarantee period and the greater the annual increase, the lower the starting income will usually be. The table above will give you an indication of the impact of the guarantee period on the starting annuity that increases by 5% a year (see table below).
3. Hybrid
You can also use a combination of the two, using some of the R5-million to buy a guaranteed life annuity that covers your essential monthly expenses – housing, food, medical aid, electricity and other costs. The balance can remain in a living annuity.
Because part of your income is then secure for life, you can draw less from the living annuity. This gives the invested capital a better chance of growing and being available for your son.
4. Capital-preservation annuity
Another option directly addresses both objectives: providing an income for life while still leaving capital to your family.
Some insurers offer a structure that combines a guaranteed life annuity with life cover equal to the original amount invested. You receive a guaranteed income for life and, when you die, the life policy pays a predetermined capital amount to your nominated beneficiary.
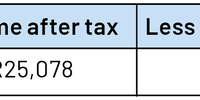
In this example, the objective is to replace the original R5-million invested. On your death, your beneficiaries would receive R5-million as a capital payment from the life policy. The advantage is that you know what income you will receive during your lifetime and what capital will be available for your family when you die.
With this structure, the amount intended for your beneficiaries can be planned for in advance. This can be particularly useful when leaving capital is not simply a nice-to-have, but an important part of the family’s financial plan. You may, for example, have a financially dependent spouse, a child with a disability or special needs who will require lifelong support, or a family member who may need money for a carer or assisted living after your death.
Having a known capital amount available can make planning for those future costs much easier.
The key is not to choose the option that simply offers the highest starting income. Start with the income you actually need, decide how much certainty you want, and then consider how important leaving an inheritance is to you.
At 65, your R5-million needs to provide for you potentially for another 35 years, so your own financial security must come first. However, with careful planning, you can have a sustainable retirement income and still leave something meaningful to your son. DM
This story first appeared in our weekly DM168 newspaper, available countrywide for R39. The e-edition of Daily Maverick’s weekly newspaper, DM168, is now free for readers who are signed into their Daily Maverick account. Click on the cover of the newspaper below to access the e-edition.
Comments
Scroll down to load comments...